Non-performing loans
A property perspective.
A closer look at the loan.
Randy Capital Investments evaluates non-performing mortgage loans secured by residential real estate. We look at the home behind the note and the details that shape a potential purchase.
Start a conversation
Our NPL focus
Residential loans
at a turning point.
A non-performing loan is a loan that is no longer being paid as agreed. For a lender or note holder considering a sale, the next step begins with understanding the asset.
Our focus is residential mortgage debt. We evaluate opportunities individually, considering the collateral, payment history, lien position, available documentation, and current status.
Each opportunity receives its own review. Purchase terms and timing depend on what that review shows.
What we review
The home.
The documents.
The full picture.
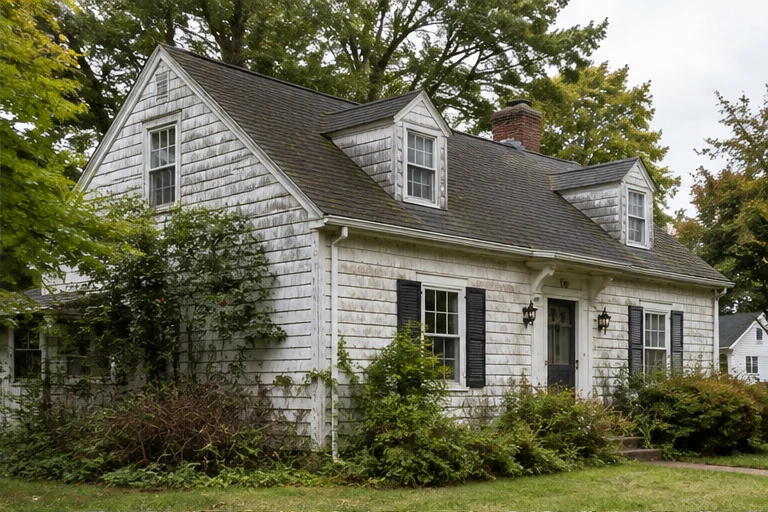
Residential collateral
Location, property type, condition, and available information about the underlying home.
Loan information
The unpaid balance, payment history, loan terms, and current status.
Lien and title details
The recorded mortgage, lien position, and other claims that may affect a potential purchase.
A workable transaction
The seller’s objectives, available documents, purchase conditions, and proposed timing.
For lenders & note holders
Start with
the essentials.
Share a general overview of the residential loan you are considering selling. We can discuss the next steps for a detailed review if it falls within our focus.
The property
Where it is located and the type of residential home securing the loan.
The loan
General balance, performance status, and available documentation.
Your goals
What you hope to accomplish and your preferred transaction timeline.
01Who can contact you about a loan?
Lenders, private note holders, and authorized representatives can reach out about residential non-performing mortgage loans.
02Is this a loan application?
No. This page is for holders considering selling an existing residential mortgage loan.
03How is a potential purchase reviewed?
We consider both the underlying residential property and the loan documents. Any offer depends on the specific asset and the findings of that review.
04What should I send initially?
Start with the property location, general loan status, and your contact information. We can discuss how to share detailed documents after the initial conversation.
Let’s connect
Have a residential loan
you’re ready to discuss?
Tell Randy about the property, the situation,
and what you would like to do next.